The Federal Reserve raised interest rates Wednesday for the first time in more than three years, and for anyone who owns, buys or invests in real estate, this is something worth paying attention to.
The Federal Reserve increased its benchmark rate by a quarter percentage point, bringing its target range to 3.75% to 4%.
Why raise rates?
One of the Fed’s primary responsibilities is controlling inflation. When inflation runs too high, increasing interest rates makes borrowing more expensive. That tends to slow spending and investment, reducing demand and eventually taking some pressure off prices.
The challenge today is that some inflation is being driven by factors that interest rates cannot easily fix. Higher oil and energy prices connected to the conflict with Iran are filtering into transportation, manufacturing and ultimately the cost of consumer goods. As The Washington Post reported, those pressures are complicating the Fed’s efforts to control inflation.
Real estate is where higher rates become very tangible.
Mortgage rates were already approaching 7% before Wednesday’s announcement. According to Freddie Mac, the average 30-year mortgage was 6.76% as of Sept. 10, compared with 5.98% in late February.
For investors, that changes the math quickly.
A property that produced an acceptable return with financing at 5.5% may not work at 7%. Higher debt service reduces cash flow, lowers the price an investor can afford to pay and makes it harder for sellers to justify yesterday’s valuations.
Residential buyers face the same problem. They aren’t necessarily deciding that they don’t want a particular house. Their monthly payment may simply tell them they can’t afford it.
That can eventually put downward pressure on prices, particularly if higher rates remain with us for an extended period.
But real estate investors should also remember that changing markets create opportunities.
When financing becomes more expensive, competition can decline. Properties can sit longer. Sellers may become more willing to negotiate. Investors with cash, lower leverage or the ability to improve a property’s income can find opportunities that weren’t available when inexpensive money had buyers competing for virtually everything.
I don’t think the lesson is to stop investing in real estate.
The lesson is that the numbers matter more than ever. Investors need to be disciplined about purchase price, financing costs, cash flow and their ability to hold an asset through a changing market.
Higher interest rates don’t eliminate real estate opportunities. They change where those opportunities are found.
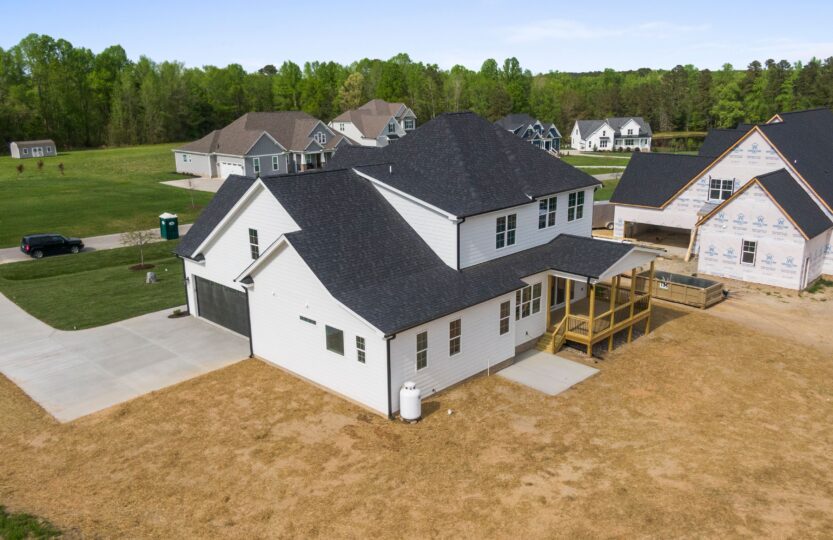
Photo Credit Curtis Adams via Pexels.